
Trust, but Verify: When the Experts Get It Wrong


The Debate
Is “MRA + 10” an eligible retirement combination for an immediate pension, deferred pension, or both?
To be clear, this article was written with immense respect for the work done by human resources (HR) personnel, the Office of Personnel Management (OPM), employee unions, professional associations, and others who support federal employees with their pay and benefits. This is not a criticism, but instead a reminder that when it comes to pay and benefits, it’s critical that employees review and validate the information they receive.
Before we dive into what happened, let’s agree on a few basic truths:
(1) Federal benefits and financial planning can get very confusing, very quickly. CSRS, FERS, FSPS, FSRDS, MRA, RMD, RSCD, SCE, RAS, FRA, HSA vs. FSA, FEDVIP, FEGLI, FEHB, FLTCIP...it’s a sea of acronyms that are deciphered with other acronyms.
(2) HR personnel processing retirement paperwork and answering questions from employees are overworked and constantly buried under a growing queue. They’re human, and humans make mistakes.
(3) Nobody knows everything. Not me, not HR, not your union rep, not your financial planner, not your accountant, not your angsty teenager, and certainly not the salty GS-15 telling war stories all day. If anyone claims to know it all, you should run the other way. A little humility goes a long way.
The Basics: MRA + 10
(1) MRA = “Minimum Retirement Age”, which for anyone born in 1970 or later is age 57.
(2) 10 = 10 years of creditable federal civilian service.
OPM’s guidance is clear that MRA + 10 is an option for an immediate pension. Straight from the source: “An MRA+10 retirement allows you to retire with retirement benefits beginning immediately after you have completed at least ten years of service and have reached your Minimum Retirement Age.”
The Confusion
A fellow agent, Jerry, reached out to me for some guidance. Jerry and his wife, Elaine, are both feds and are nearing the retirement finish line. They both work for the U.S. Department of State as Foreign Service Special Agents (primary skill code 2501), covered by the Foreign Service Pension System (FSPS). Think of them as 1811 federal agents with an added international twist.
Foreign Service Special Agents occupy a unique middle ground: they follow the same baseline pay, benefit, and retirement rules of non-law enforcement Foreign Service Officers (FSOs) while also receiving select law enforcement officer (LEO) perks. For example, Law Enforcement Availability Pay (LEAP), early penalty-free access to their TSP, and the health/long-term care insurance premium Public Safety Officer deduction.
Elaine is an FS-02 (Civil Service GS-14 equivalent) and will be 45 years old this year with 24 years of creditable federal civilian service under FSPS.
The basic retirement eligibility hurdle for FSOs is age 50 + 20 years of service. This 50/20 combination entitles an FSO to:
(1) An immediate unreduced pension (referred to as an “annuity” by the government)
(2) Health insurance for life (FEHB eligibility for retirees/annuitants can be found here)
(3) Cost-of-living-adjustments (COLAs) prior to age 62
(4) 1.7% for the first 20 years of service and 1% for each subsequent year
(5) Retiree Annuity Supplement (RAS) with no earnings test prior to MRA
For you FERS Special Category Employees (SCE), this should look very familiar. SCEs (also referred to as “special provisions” and “special group” employees) include federal law enforcement personnel, firefighters, air traffic controllers, nuclear materials courier, Supreme Court Police, and Capitol Police.
So, we know that Elaine doesn’t meet the 50/20 eligibility, so what options does she have as an FS-02 who is under age 50, has 20+ years of service, but wants to retire?
(1) Request a refund of all the money she paid into FSPS and give up the entitlement to a pension.
(2) Leave her pension contributions in the system, return to the Foreign Service in the future, and then retire with an immediate pension when she has reached age 50.
(3) Wait until she reaches her Minimum Retirement Age (MRA) and begin collecting a DEFERRED pension. This deferred pension at MRA with 20 years of FSPS credit would result in:
A pension calculated at 1% per year (not 1.7%)
No FEHB (health insurance)
No COLAs until age 62
No RAS
But because she has 20+ years of FSPS service, there would be no age-based reduction. This is a big deal and is unique to FSPS. This deferred MRA + 20 deal that eliminates the age-based reduction does not apply to Civil Service employees who fall under FERS.
If a Civil Service (FERS) federal employee receives what’s known as an “MRA + 10” pension (whether immediate or deferred), their pension is subject to a penalty of 5/12 of 1% for each full month prior to age 62. This means that someone using the MRA+10 eligibility qualification at age 57 will have their pension permanently reduced by 5% per year if they don’t wait until age 62, or wait until age 60 with 20 years of service, or wait until MRA with 30 years of service (in which case the reduction penalty is not applicable).
Here’s where things went off the rails.
Jerry shoots me a text stating that Elaine just spoke to her HR retirement counselor, George, and was told that if she separates from federal service this year (age 45 + 24 years of service), she cannot start receiving her pension until age 62.
Luckily, Jerry has read a few of my rambling articles in the past, so he thought this sounded incorrect. Jerry thought (correctly) that an MRA+10/MRA+20 deferred pension could be started upon reaching MRA (age 57 for Elaine). Looking for some serenity, Jerry asked me for guidance.
Knowing that MRA+10 is an eligible combination for both an immediate and deferred pension, I reached out to an employee association that helps advocate for FSOs, hoping that maybe they could speak to the HR retirement team to clear this up.
Here’s where things got even more confusing.
After firing off an email to the employee association, I got a response from someone we’ll call Kramer. Kramer told me that the retirement counselor was in fact correct. Kramer stated that Elaine would only be eligible for a deferred pension at age 62, not upon reaching her MRA.
I immediately experienced that sinking feeling you get when you hear something that contradicts a belief you’ve always held. Could I have been misunderstanding deferred pensions this whole time? Have I posted inaccurate information and given inaccurate advice for years?
I quickly checked all of the official sources: the Foreign Service Act, Title 5, GRB publications, OPM guidance, FERS handbook, etc. Luckily, these sources confirmed that I had not made up a type of deferred retirement in a fever dream.
I went back and forth via email with Kramer a few times. He suggested that maybe I was confused on the definition of “deferred” versus “postponed”...a very important distinction in the world of federal retirement, but not the issue today. Kramer even cited a section of the Foreign Affairs Manual (FAM), which as someone who loves sourced facts, I appreciated. However, when I read the FAM reference carefully, it actually supported what I was saying.
I finally made one last attempt with every source I could find to clearly show that a “deferred MRA + 10” retirement is a real-life thing. If you ever find yourself in this situation, don’t rely solely on articles or blog posts from financial planners, benefit experts, or reputable media sources (Fedweek, GovExec, Fed Smith, Federal News Network, etc.). They might point you in the right direction and be accurate, but when it comes to communicating with HR, you need to cite actual legal/government sources.
These are the six sources I emailed them to support my claim that a deferred pension can be started at MRA:
(1) 3 FAM 6142.2
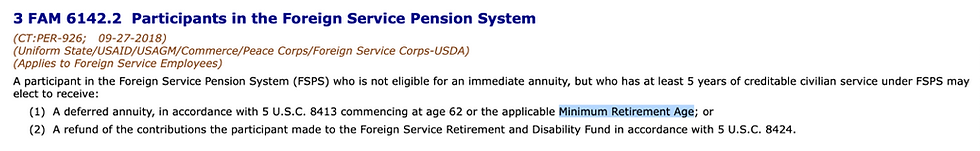
(2) Foreign Service Act, Section 855

(3) 5 U.S. Code § 8413(b)

(4) OPM Deferred Retirement webpage

(5) Government Retirement & Benefits (GRB) Publication

(6) American Foreign Service Association (AFSA) Publication

Kramer responded and apologized, explaining that it was an oversight when reading the FAM. He confirmed that the deferred pension CAN be started at MRA and if the employee had 20+ years at the time of separation, their pension would NOT be subject to an age-based reduction.
Important Note: There are many sources out there that still say that an FSPS Deferred MRA+20 pension will be calculated using 1.7% vs. 1% - this is not the case. Both HR and AFSA have confirmed that deferred pensions, even with 20 years of service, will be calculated using a 1% multiplier.
This makes sense when you look at how FERS handles Special Category Employees who separate from service prior to meeting the (1) age 50 + 20 years of service or (2) any age + 25 years of service combination. In that situation, they aren’t entitled to the special provision retirement computation using 1.7% because they aren’t retiring with an immediate SCE pension.
Chapter 54, page 11 of the FERS Handbook says that “special benefits” ONLY apply to employees who separate with an immediate annuity under special provisions. Therefore, the regular MRA+10 and deferred retirement rules that apply to everyone (1% multiplier), also apply to SCE employees who separate before meeting the age-and-service requirements under special provisions. If you don’t cross an SCE threshold, you’re not entitled to the SCE benefits (1.7% multiplier).

Key Takeaway
This is not a “gotcha” article. It’s a reminder that humans make mistakes, even those in positions of authority. Mistakes around retirement and financial planning can have huge ripple effects, which is why it’s so important to verify everything.
If Jerry and Elaine didn’t question the authoritative sources, they could have been faced with:
(1) Giving up 5 years of pension payments with no age-based reduction.
(2) Spending down more retirement assets (IRA, TSP, brokerage accounts) while they waited to turn on the pension at age 62.
(3) Having to work longer in their post-retirement jobs to bridge an income gap.
(4) Less spending, less enjoyment, fewer vacations with the family, etc.
This stuff really matters.
With OPM, HR, and the payroll teams being understaffed and overworked, the burden is on us as employees to double-check everything. I strongly recommend reviewing every single Leave & Earnings Statement.
-Are you getting paid at the correct pay rate?
-Is your address/state correct for state tax purposes?
-Are you getting paid for the correct number of hours?
-Are you receiving all the premium pay you're entitled to?
-Do you understand every deduction being taken from your paycheck?
A quick side note on deductions – I had someone getting ready to retire in their 60s. They still had FEGLI life insurance coverage and were paying an astronomical amount each year. I asked them what made them choose to keep FEGLI this long? They had no idea. They thought FEGLI was a mandatory deduction. Even worse, they had no need or desire for life insurance.
When you get your retirement estimate, double-check your numbers to ensure you’re getting what you’re entitled to. I know it’s a pain, but it’s your money and your future.
About the Author
Tyler Weerden is a fee-only financial planner, Enrolled Agent, and the owner of Layered Financial, a Registered Investment Advisory firm based in Arlington, Virginia. In addition to being a financial planner, Tyler is a full-time federal agent. He holds a Bachelor of Science degree, a Master of Science degree, passed the Series 65 exam, and is a Certified Fraud Examiner (CFE). Tyler is the sole Investment Adviser Representative at Layered Financial.
Prior to becoming a federal agent, Tyler served as a state trooper, local police officer, and was a member of the U.S. Army National Guard. He has served in both domestic and overseas Foreign Service assignments. Tyler has experience with local, state, and federal pension systems, 457(b) Deferred Compensation, the federal Thrift Savings Plan (TSP), Individual Retirement Accounts (IRAs), Health Savings Accounts (HSAs), and various investment options to include rental real estate.
Disclaimer
Layered Financial is a Registered Investment Adviser registered with the Commonwealth of Virginia, the State of Texas, and the State of Connecticut. Registration does not imply a certain level of skill or training. The views and opinions expressed are as of the date of publication and are subject to change. The content of this publication is for informational or educational purposes only. This content is not intended as individualized investment advice, or as tax, accounting, or legal advice. Nothing in this article should be seen as a recommendation or advertisement. Layered Financial and its Investment Advisor Representatives have no third-party affiliations and do not receive any commissions, fees, direct compensation, indirect compensation, or any benefit from any outside individuals or companies. Although we gather information from sources that we deem to be reliable, we cannot guarantee the accuracy, timeliness, or completeness of any information prepared by any unaffiliated third-party. When specific investments, types of investments, products, or companies are mentioned, such mention is not intended to be a recommendation or endorsement to buy or sell the specific investment, solicit the business, or use that product. The author of this publication may hold positions in investments or types of investments mentioned in articles. This information should not be relied upon as the sole factor in an investment-making decision. Readers are encouraged to consult with professional financial, accounting, tax, or legal advisers to address their specific needs and circumstances.
© 2026 Tyler Weerden. All rights reserved. This article may not be reproduced without express written consent from Tyler Weerden.


